
Beaufort · Fripp Island · Bluffton · Hilton Head · Charleston
Mortgages and reverse mortgages for Beaufort and the South Carolina Lowcountry
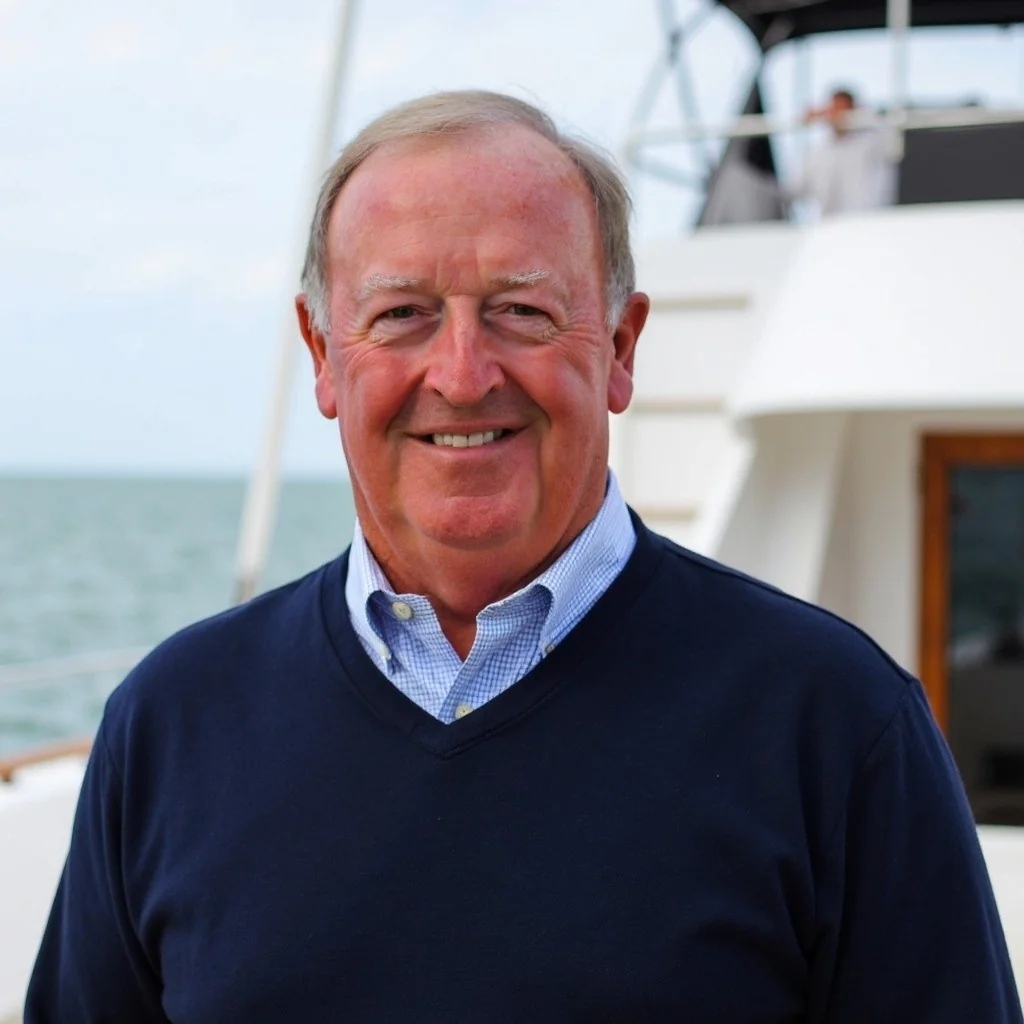
Billy Peel spent years on Fripp Island, where his group owned the Fripp Island Real Estate Company. Today he and Samantha help Lowcountry buyers and homeowners compare their financing options in plain language.
Licensed mortgage broker in South Carolina & Georgia · NMLS #2694379
Who we help in the Lowcountry
The Lowcountry attracts retirees, military families, and buyers moving from out of state. Each brings different questions about financing.
Retirees relocating to the Lowcountry
A HECM for Purchase may let buyers 62 and older combine their own funds with an FHA-insured reverse mortgage to buy their next home, without a required monthly mortgage payment*. It can help keep more savings available after the move.
How HECM for Purchase worksMilitary and local buyers
Conventional, FHA, VA, and USDA loans for buyers across Beaufort, Jasper, and Charleston counties, including families at MCAS Beaufort, MCRD Parris Island, and Joint Base Lindsey Graham (formerly Joint Base Charleston). First-time buyers can ask about SC Housing programs.
Explore home purchase loansHomeowners refinancing or using equity
Compare refinancing an existing mortgage, tapping home equity, or, for homeowners 62 and older, a reverse mortgage on the home you already own.
Explore refinancing
*Borrowers must continue to pay property taxes, homeowners’ insurance, and maintain the property. The loan becomes due when the last borrower leaves the home or sells it.
What’s different about buying in South Carolina’s Lowcountry
South Carolina’s property tax rules and the coast’s flood rules can change what a home really costs. These are worth knowing before you buy.
The 4% primary-residence tax rate
South Carolina assesses an owner-occupied legal residence at 4% of its value, compared with 6% for second homes and other property, and the primary home is also exempt from school operating taxes. It is not automatic: apply with the county assessor, such as the Beaufort County Assessor, by the county’s deadline.
Homestead exemption at 65
Homeowners who are 65 or older (or totally disabled or legally blind) and have lived in South Carolina for a full calendar year may exempt the first $50,000 of their home’s value from property taxes. Apply through the county auditor. SC Department of Revenue details.
Flood zones and barrier islands
If any part of a home is in a FEMA Special Flood Hazard Area, most mortgages, including FHA loans and HECMs, require flood insurance. FHA also cannot insure homes in the federal Coastal Barrier Resources System, which includes some barrier-island property, so check early. Start with the FEMA Flood Map Service Center.
A HECM has to be your main home
A reverse mortgage can only be used on your principal residence, so a beach house or vacation home is not eligible. With a HECM for Purchase, you generally need to move in within 60 days of closing.
Our Lowcountry roots
In 2003, Billy and his investment partners formed The Fripp Group LLC and acquired the Fripp Island Real Estate Company, along with other business operations on Fripp Island. Billy served in senior ownership and management roles there while continuing to run Mortgage Capital Services.
After selling his interest in The Fripp Group, Billy returned his primary business to the Augusta area, but the Lowcountry remains part of how we work. We understand the island communities, the coastal property questions, and the retirees who come here for the next chapter.
Read Billy’s full backgroundCommunities we serve in the Lowcountry
We work with clients across coastal South Carolina by phone and video, and we’re glad to travel to meet you in person.
- Beaufort
- Port Royal
- Lady’s Island
- Fripp Island
- Harbor Island
- Bluffton
- Hilton Head Island
- Charleston
- Mount Pleasant
- Summerville
Common questions
Lowcountry mortgage questions
Can I use a reverse mortgage to buy a home in the Lowcountry?
Possibly. A HECM for Purchase may let a buyer 62 or older purchase a principal residence using their own funds plus reverse mortgage proceeds. The home must meet FHA property standards, you must complete independent HUD-approved counseling, and you remain responsible for property taxes, insurance, and maintenance.
Can I use a reverse mortgage on a beach house?
No. A HECM must be the principal residence of each borrower. Second homes and vacation homes are not eligible.
Will my South Carolina home be taxed at the 4% rate?
Only if it is your legal residence and you apply. South Carolina assesses an owner-occupied primary home at 4%, versus 6% for other property, but you must file with the county assessor by the county’s deadline.
Are you licensed to lend in South Carolina?
Yes. Mortgage Capital Services, LLC (NMLS #2694379) is licensed in South Carolina and Georgia. You can verify our licensing through NMLS Consumer Access.
Start here
Talk with us about your Lowcountry move
Tell us where you plan to buy or what you want to change about your current mortgage. Samantha will follow up to talk through your options.
Important: This page is educational and is not financial, legal, or tax advice, or a commitment to lend. All loans are subject to credit approval, property eligibility, and program requirements. A reverse mortgage is a loan that must be repaid and reduces home equity over time. Reverse mortgage borrowers remain responsible for property taxes, homeowners insurance, and maintenance, and HECM borrowers must complete independent HUD-approved counseling. Proceeds may affect eligibility for some need-based benefits. This material is not from HUD or FHA and was not approved by HUD, FHA, or any government agency. Property tax rules are set by state and county offices and can change; confirm with your county before relying on them. Mortgage Capital Services, LLC NMLS #2694379 · Billy D. Peel NMLS #332044 · Samantha S. Peel NMLS #2685482 · Licensed in Georgia & South Carolina · Equal Housing Opportunity.