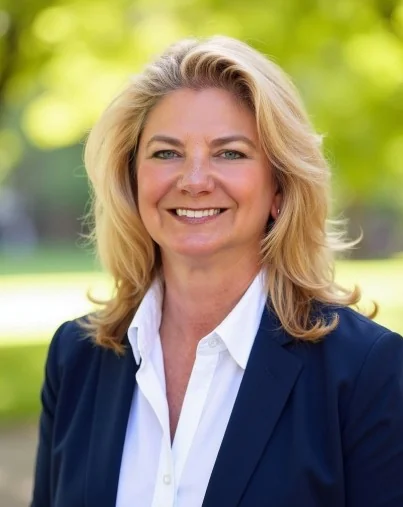
Reviewed by Samantha S. Peel, Mortgage Loan Officer
NMLS #2685482 · Licensed in Georgia & South Carolina · More than 12 years working with seniors and their families in senior living before joining MCS. Last reviewed September 26, 2026.
Start with the situation, not the product
Lenders organize information by product name: HECM, HELOC, refinance, proprietary reverse. Families do not think that way. They think about a person and a problem. Find the situation closest to yours below, and you will get a comparison of everything available for it — loans and otherwise — with an honest account of when each one is a bad idea.
The most common question we hear, and the one least often answered by a mortgage product alone.
- Reverse mortgage and HECM line of credit
- HELOC, home equity loan, cash-out refinance
- Senior property-tax exemptions and benefits
- Doing nothing for six months
- Selling and moving
Compare the options →
In-home care, assisted living, or memory care — in roughly the order families should consider the funding sources.
- Long-term care insurance
- VA Aid and Attendance
- Medicaid and elder-law planning
- Home equity options
- Selling the home
Compare the options →
The most overlooked option, and often the one that works. The real question is how to pay for the next place.
- Paying cash from the sale proceeds
- HECM for Purchase
- Conventional and government-backed loans
- Proprietary reverse for purchase
- Renting instead of buying
Compare the options →
After the loss of a spouse. Our usual advice here is to wait, which costs us business and is still the right advice.
- Why waiting is usually right
- Assuming the existing mortgage
- Refinancing in the survivor's name
- Reverse mortgage considerations
- Selling
Compare the options →
Part financial, part something else. Both parts deserve an honest hearing, and they are easier apart.
- Selling outright
- Selling and buying smaller
- Keeping it and borrowing against it
- Renting it out
- Holding and deciding later
Compare the options →
What you can expect from a conversation with us
We are a small, local team. Billy has been in mortgage and real estate in this region since the 1980s, and Samantha spent more than twelve years working with seniors and their families in senior living before joining the firm. That background shapes how we approach these conversations.
- A conversation is not an application, and there is no cost for it.
- We will ask about health, family, and plans before we ask about the house, because those determine whether any financing makes sense.
- If the right answer is selling, waiting, calling an elder-law attorney, or applying for a benefit, we will say so, even though none of those pay us.
- We will not ask an adult child to make a decision for a parent who can make their own, and we will not ask a parent to decide without family present if they want them there.
- Independent counseling is required before any FHA-insured reverse mortgage. We consider that a good thing and we will never steer you toward a particular counselor.
Free community sessions
We present no-cost educational sessions for senior communities, churches, libraries, and civic groups across the CSRA and Lowcountry. They are not sales presentations — they cover how these options work, what they cost, and when they are a bad idea. If your organization would like to host one, or you would like to attend the next one, get in touch.
Independent places to check our work
You should never take a lender’s word as the only word. These organizations are not affiliated with Mortgage Capital Services and do not pay us or receive payment from us.
Important: This page is educational and is not financial, legal, or tax advice, a recommendation, or a commitment to lend. Loan program availability, costs, and requirements are set by lenders and investors and may change. All loans are subject to credit approval and property eligibility. Reverse mortgage borrowers remain responsible for property taxes, homeowners insurance, property maintenance, and other loan obligations. Loan proceeds may affect eligibility for Medicaid, Supplemental Security Income, and other needs-based benefits. Consult a qualified financial, tax, or legal advisor about your own circumstances. Mortgage Capital Services, LLC, NMLS #2694379 · Samantha S. Peel, NMLS #2685482 · Licensed in Georgia & South Carolina · Equal Housing Opportunity.